 By Miah Ayaan
Interest Rates Now Shape Buyer Behavior More Than Prices
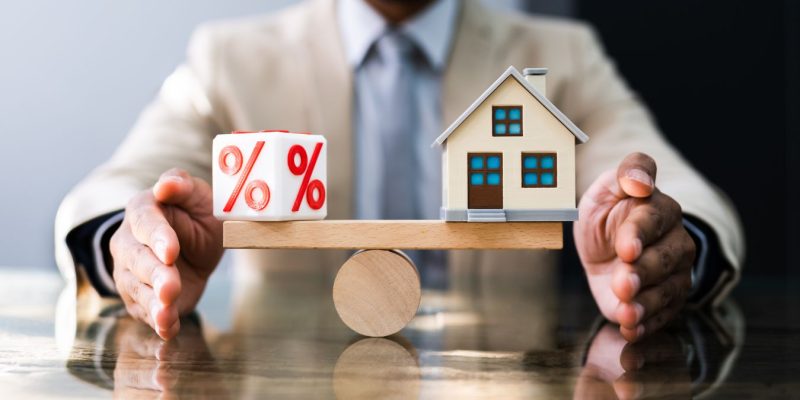
In 2026, interest rates have become one of the most influential forces in Singapore’s property market. While property prices remain relatively stable due to regulation and controlled supply, even small changes in borrowing costs can significantly affect buyer sentiment, affordability, and transaction volume.
This makes interest rate sensitivity a key factor in both investment and owner-occupier decisions.
Monthly Repayments Are the Real Decision Driver
Most buyers are no longer evaluating property purely based on headline price. Instead, they focus on monthly repayment affordability. A small increase in interest rates can translate into a noticeable rise in monthly mortgage obligations.
This directly affects:
- Loan eligibility comfort
- Debt servicing ratios
- Long-term financial planning
As a result, financing conditions now heavily influence demand levels.
Psychological Impact Is as Important as Financial Impact
Interest rates do not just change numbers—they change behavior. Even when buyers can technically afford higher repayments, many become more cautious when rates rise.
This creates a psychological slowdown in decision-making, even if fundamentals remain unchanged.
Refinancing Expectations Influence Market Sentiment
Many buyers in 2026 factor in future refinancing scenarios when making purchase decisions. Expectations of rate cuts or stabilization can encourage demand, while uncertainty can delay decisions.
This creates a sentiment-driven layer on top of financial logic.
Higher Rates Reduce Speculative Activity
One of the key effects of higher interest rates is the reduction of speculative buying. Investors become more selective and focus on sustainable cash flow rather than leverage-driven gains.
This leads to a more stable but slower-moving market.
Impact on Entry-Level and Mid-Tier Buyers
Mid-tier buyers are most sensitive to interest rate changes. This group often relies on financing and is therefore more exposed to changes in monthly repayment obligations.
As a result, affordability thresholds shift quickly when rates move.
Rental Market Interaction With Interest Rates
Interest rates also influence rental behavior. When mortgage costs rise, some investors rely more heavily on rental income to offset expenses, increasing focus on tenant stability and occupancy rates.
This strengthens the link between financing conditions and rental strategy.
Location Quality Becomes a Buffer Against Rate Sensitivity
Well-located properties tend to be less sensitive to interest rate fluctuations because they maintain stronger demand across cycles. Buyers are more willing to proceed when they perceive long-term value stability.
Developments such as Lucerne Grand benefit from this effect due to their accessibility and strong positioning, which helps sustain buyer confidence even in higher-rate environments.
Suburban Markets Experience Stronger Sensitivity
Suburban properties tend to be more affected by interest rate changes because buyers in these segments are often more price-sensitive and budget-conscious.
This can lead to slower absorption during higher-rate periods.
Financing Structure Matters More Than Ever
Buyers are increasingly comparing fixed vs floating rate packages and stress-testing their financial positions before committing. Financing structure is now a key part of property selection.
This adds complexity to decision-making but improves long-term financial discipline.
Lifestyle Value Helps Maintain Demand Stability
Even in higher-rate environments, lifestyle-driven demand remains relatively resilient. Buyers who prioritize living experience may still proceed with purchases if the property fits their long-term needs.
Island Residences reflects this trend by appealing to buyers seeking a more relaxed residential environment while still maintaining access to urban infrastructure, helping maintain demand stability even under changing interest rate conditions.
Interest Rates Create Cyclical Buying Opportunities
While higher rates slow demand, they can also create long-term opportunities. Some buyers enter the market during high-rate periods expecting future stabilization, positioning themselves for potential capital gains later.
This creates natural market cycles.
Conclusion
Interest rate sensitivity is one of the most important forces shaping Singapore’s 2026 property market. It influences affordability, buyer psychology, financing decisions, and overall transaction volume.
While the market remains fundamentally stable, even small rate changes can significantly shift behavior. Developments such as Lucerne Grand and Island Residences demonstrate how strong positioning and lifestyle appeal help maintain buyer confidence and demand resilience across different interest rate environments.